In the
June Outlook and
members’ webinar we expressed our growing concerns about inflation and the potential for it to push interest rates higher, which could potentially lead to additional market volatility through the summer months and possibly a pullback. Our concerns were not alleviated by this week’s inflation data. Consumer inflation, measured by the Consumer Price Index (CPI), hit 4.2% year-over-year, its highest level in nearly three years. Any hope for potential relief was then dashed when the Producer Price index (PPI) was released earlier today as it showed prices rising briskly in May to 6.5% year-over-year.
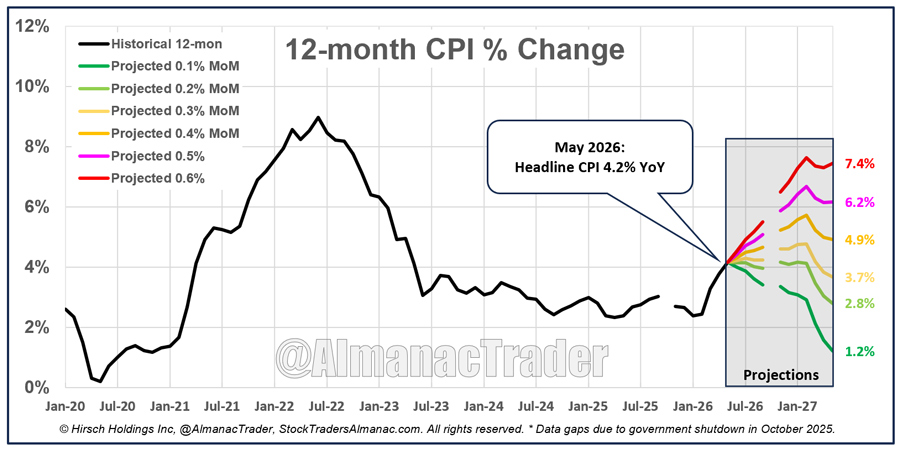
As the accompanying chart illustrates, the inflation story may be far from over. The black line shows the historical 12-month CPI trend, while the colored projections model various monthly inflation scenarios over the next year. Even under relatively modest monthly increases of 0.3% to 0.4%, annual CPI remains elevated in the 3.7%–4.9% range through mid-2027. More concerning is what happens if monthly inflation remains closer to the 0.5%–0.6% pace that has surfaced recently. In those scenarios, headline CPI could climb back above 6% and potentially approach 7.4%.
Higher inflation has forced the Federal Reserve to maintain a neutral policy stance longer than expected and is likely to make it consider additional tightening if inflation proves stubborn. Next week’s FOMC meeting announcement will likely highlight its growing concerns with inflation. Historically, periods of rising inflation expectations have coincided with higher bond yields, increased equity market volatility, and pressure on valuation multiples.
While inflation alone does not guarantee a market correction, the combination of elevated valuations, seasonal summer weakness, and renewed inflation concerns argues for a more cautious stance in the months ahead. Remain focused on risk management and be prepared for the possibility that inflation, and interest rates, becomes the market’s primary concern.
Today’s rally indicates that many traders and investors are still positioning for a benign inflation outcome, lower crude prices, and a quick easing of Middle East risk. Our concern is that if inflation fails to retreat quickly, that optimism may be challenged later in Q3.
NASDAQ Seasonal MACD Update
NASDAQ’s Seasonal MACD indicator entered June in negative territory. It remains negative as of today’s close. Because our sell signal requires a new negative crossover (using 12-26-9 parameters) on or after the first trading day in June, the indicator must first turn positive before it can trigger. Currently NASDAQ would need to gain at least 3462.98 points (13.42%) in a single day to turn its MACD positive.
A quick note about this seemingly insurmountable daily move. MACD uses exponential moving averages in its calculation that do give more weight to the most recent values. Today’s gain did reduce the one-day move substantially and it also reversed the trend of MACD’s histogram (the vertical bars above and below the zero/horizontal line in the MACD section of the chart). The trend of the histogram does precede a crossover in MACD as it represents the difference between MACD and its signal line. As the difference falls, the lines are moving closer together. The trend can continue as long as NASDAQ moves sideways and/or higher.
Last year, NASDAQ’s MACD took a comparable path to this year. It entered June in negative territory, turned positive in late-June just as NASDAQ’s Midyear Rally began, and remained positive until July 14, 2025. Because NASDAQ’s Midyear rally is primarily driven by quarterly earnings release expectations, it is reasonable to anticipate a similar trajectory this year. Continue to hold positions in QQQ and IWM.
When NASDAQ’s Seasonal Sell signal criteria are satisfied, we will send an email to all members. At that time, we will finish repositioning the Portfolios for the “Worst Months.” We still anticipate adding to some or possibly all of the existing bond ETFs and cash holdings in the Tactical Seasonal Switching Strategy portfolio.
Dividend Stock Basket – New Trade Ideas
This basket is being presented in advance of NASDAQ’s “Worst Four Months” of the year (July through October) and the worst two-month stretch for stocks, August and September. We will look to add these 10 stocks, in the table below, just below current levels on minor to modest dips. Some of the positions did strengthen in today’s trading session but there is no need to rush. As a reminder, the buy limit is our suggested maximum price to pay, and the stop loss only applies if the position closes the regular day session below it. For tracking purposes, we will allocate a hypothetical $3000 from the cash position in the Almanac Investor Stock Portfolio to each position.
For each stock we have provided the ticker, name, sector, general business description, PE, price-to-sales ratio, market value, current price, a dividend yield and a suggested buy limit and stop loss. There is also a link above the table to download the table in an Excel file (.xls format). This should aid importing and researching these stocks as most trading platforms and research software have support to import a stock list.
The overarching theme for this basket was dividend yield along with belonging to a traditional defensive sector with a history of outperforming the S&P 500 during the “Worst Months,” May through October. Many of the names are familiar and you may have some of their products in your own home. Many of these stocks have also been left for dead as they struggle with higher input costs and a consumer that many believe is stretched to the limit. Technically, these stocks appear to be showing signs of renewed interest now that expectations have retreated.
Additionally, we set a floor of $500 million for market capitalization and an average daily volume of 500,000 shares over the last 20 trading sessions in an effort to ensure liquidity and trading access would not be an issue. Should the broader market slip into a typical Q3 seasonal slump, these names could provide some shelter while paying a relatively healthy dividend at the same time.
Click to view full size…