Key takeaways from the webinar are NASDAQ’s Midyear rally is underway, it has struggled the past couple of sessions, but strength usually runs until around mid-July. This rally is likely to provide the setup for NASDAQ’s Seasonal MACD Sell Signal and time to review positions, take profits and consider rotating into other positions for the balance of the “Worst Months.”
Iran, inflation, and stretched valuations in some sectors of the market are still market headwinds. Midterm election uncertainty is also likely to begin to grow in August, September, and October. Collectively or individually, these could easily be the catalyst for a typical midterm-year “Weak Spot” (page 46 STA 2026) market pullback.
NASDAQ Seasonal MACD Update
As of the close today, July 2, NASDAQ’s Seasonal MACD indicator remains negative. The criteria we use to issue our NASDAQ Seasonal MACD sell is a new negative crossover of MACD (using 12-26-9 parameters) on or after the first trading day in June. It would currently take a one-trading-day NASDAQ advance of 488.81 points (+1.89%) for NASDAQ’s MACD indicator to turn positive. Continue to hold associated positions in QQQ and IWM.
When NASDAQ’s Seasonal MACD registers a new negative crossover, we will send an email to all active members. At that time, we will finish repositioning our Portfolios for the “Worst Months.” We do anticipate adding to existing bond ETF and cash holdings in the Tactical Seasonal Switching Strategy portfolio.
July Sector Seasonalities
Three new sector seasonalities begin in the month of July. Bearish seasonalities for Industrials and Transports have historically begun around mid-July and lasted until around the middle of October. Technically, both sectors currently look strong with corresponding strength in iShares DJ Transports (IYT) and SPDR Industrials (XLI). Higher energy costs had been a drag in Q2, but now that crude oil has retreated, both sectors have broken out. At this time, we are going to pass on trading these bearish seasonalities. Should either begin to falter, we may consider a trade at that time.
July’s final new seasonality is for gold & silver mining stocks. This seasonality is based upon strength in the Philadelphia Gold & Silver index (XAU) that typically begins in late July and lasts until late December. Over the past 10 years, XAU has gained on average 11.07% and more recently in the last 5 years it has averaged 20.23%. After trading well over $5000 per ounce earlier this year, gold retreated to less than $4000 in late June and appears to be setting up for a typical seasonal low now. Silver’s decline this year has been even more substantial going from over $120 per ounce to less than $60 last week.
VanEck Gold Miners (GDX) is our preferred ETF to take advantage of seasonal strength in gold and silver miners. As of the close on July 1, GDX had over $22 billion in assets with a net expense ratio of 0.51%. Top five holdings of GDX include: Agnico Eagle Mines, Newmont, Barrick Mining, Wheaton Precious Metals, and Anglogold Ashanti.
Year-to-date, GDX was down –12.7% as of its July 1 close. It’s 50-day moving average crossed below its 200-day moving average in late-June, forming a historically bearish “death cross.” Our research has shown that the typically the majority of the decline has occurred by the time a death cross occurs. Stochastic, relative strength and MACD indicators are all at or near oversold levels but could turn the corner soon as GDX appears to have found support and begun to move higher. GDX can be considered at current levels up to a buy limit of $79.70. If purchased, set an initial stop loss at $69.05 and an auto sell at $106.23.
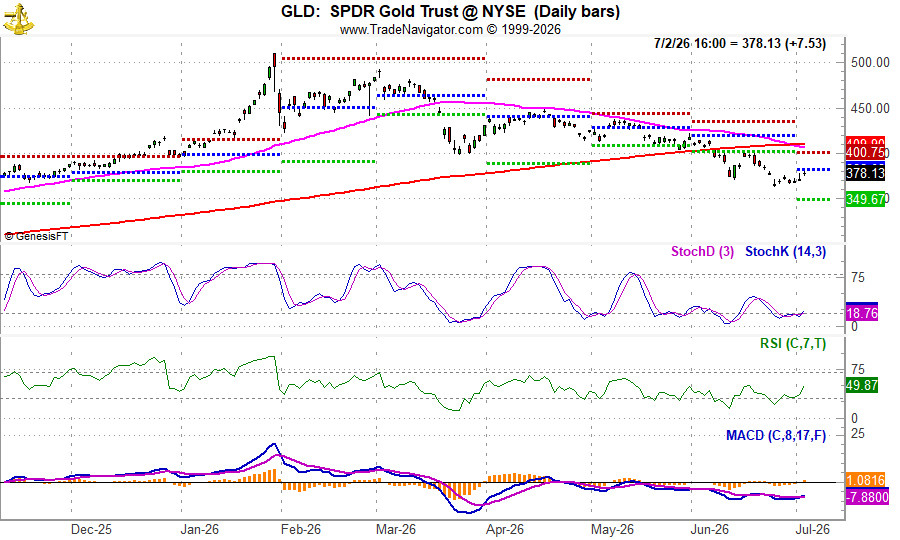
Next, we will also look to establish a position in SPDR Gold (GLD). Like the miners, physical gold was also higher today and its chart is similar to GDX. Bouncing higher off of late June lows, and a recent death cross, but with slightly better Stochastic, relative strength, and MACD indicators. GLD can be considered at current levels up to a buy limit of $382.05. If purchased, consider a stop loss at $349.25. There is no auto-sell price at this time.
VanEck Junior Gold Miners (GDXJ) is the small-cap version of GDX. The holdings of GDXJ are generally smaller market cap and early-stage miners. GDXJ has over $7 billion in assets and an expense ratio of 0.52%. Top five holdings are: Equinox Gold, Alamos Gold, Evolution Mining, Endeavour Mining, and Coeur Mining. GDXJ can be considered at current levels up to a buy limit of $103.65. If purchased, set an initial stop loss at $88.70 and an auto sell at $138.15.

Lastly, we will consider a position in iShares Silver (SLV). In recent years, silver has generally followed the trend set by gold with additional volatility and larger price swings. SLV’s chart is similar to gold with larger price swings. SLV also appears to have found support and appears to be in the early stages of a new rally. Technical indicators are showing early signs of improvement. SLV can be considered at current levels up to a buy limit of $57.65. If purchased a stop loss of $47.85 is suggested. Like GLD, there is no auto-sell price at this time.
For tracking purposes, GDX, GLD, GDXJ, and SLV will all be added to the Sector Rotation ETF Portfolio using their respective average prices on Monday, July 6.
Sector Rotation ETF Portfolio Updates
Five sector seasonalities come to an end in July but there are no associated positions currently held in the Sector Rotation ETF portfolio. They are Oil (Long), Info Tech (Long), Computer Tech (Long), Banking (Short), and Natural Gas (Short). XLE was closed out in April, IYW ran away and was not added to the portfolio. Short trades associated with banking and natural gas sectors were not selected due to corresponding strength in both.
“Worst Months” defensive positions in SPDR Consumer Staples (XLP) and SPDR Utilities (XLU) can still be considered on dips or at current levels up to their respective buy limits. Results from XLU and XLP have been mixed recently as Fed interest rate policy appears to be in a state of flux due to the recent resurgence in inflation metrics. Historically, higher rates have been a headwind for XLP and XLU. The recent decline in crude oil prices should begin to moderate inflation and potentially put the Fed back on track for lower interest rates. Lower rates would likely be solid tailwinds for XLP and XLU.
In accordance with the last ETF Portfolio update, Invesco DB Agriculture Fund (DBA) was sold and closed out of the portfolio on May 29 at $27.37 for a meager 1.4% gain. DBA could be the perfect example of where too much diversification is not good for investment returns. Fourteen different commodity holdings don’t always move in the same direction.
First Trust Natural Gas (FCG) and United States Natural Gas (UNG) were stopped out of the portfolio in early June after closing below their respective 2% trailing stop losses. FCG’s exposure to crude oil helped it avoid a loss while UNG declined 7.1%.
Healthcare and biotech positions, XLV, IBB, and XBI all surged in June and were up an average of 14.0% at the close on July 1. XLV, IBB, and XBI are on Hold.
IDV, EFAV, EFV are on Hold.
Tactical Seasonal Switching Strategy Portfolio Update
Continue to Hold QQQ and IWM. NASDAQ’s Seasonal MACD Sell Signal has NOT triggered.
Defensive positions in bond ETFs, TLT, AGG, BND, SHV and SGOV, are still flat to slightly negative excluding dividends and any trading fees. TLT, AGG and BND are on Hold. The performance of TLT, AGG and BND will likely depend greatly upon the direction of inflation metrics and the Fed. Our preferred bond ETFs are SHV and SGOV as both exhibit relatively stable pricing and have yields above 3%. We will consider adding to SHV and SGOV positions when NASDAQ’s Seasonal Sell signal triggers, but they can be considered at current levels up to their respective buy limits.
Disclosure note: Officers of Hirsch Holdings Inc hold positions in EFAV, EFV, IBB, IDV, IWM, QQQ, SGOV, TLT, TQQQ, XBI, XLP, XLU and XLV in personal accounts.